In a small country, technological changes are immediately noticeable. Improvements in infrastructure quickly affect everyday life, while a wrong decision can have tangible consequences. That is why Andorra’s digitalisation is not merely a technical matter – it is a discussion about trust, sustainability, and competitiveness.
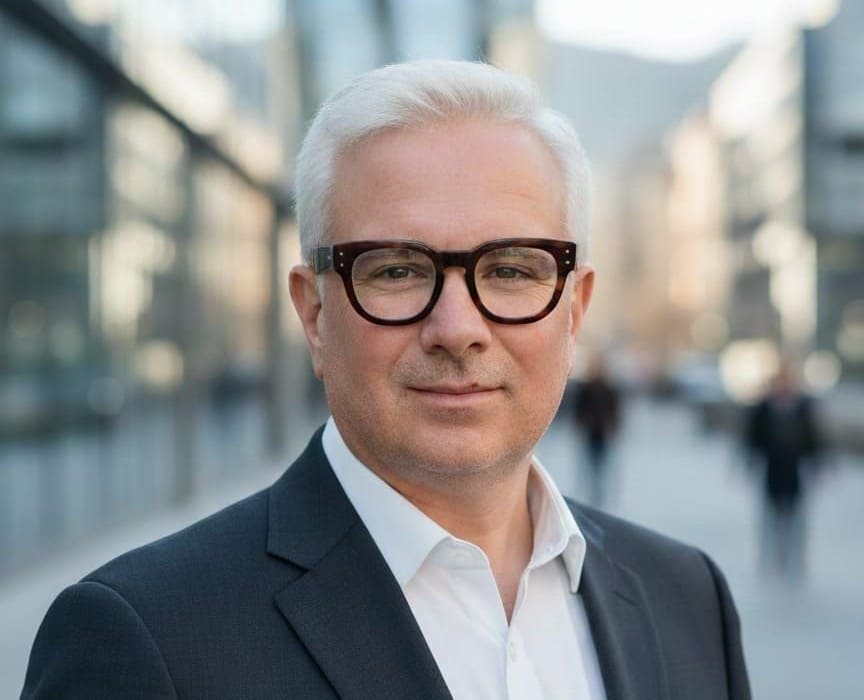
Carlos Salinas, a risk management specialist and initiator of innovative projects in digital assets within the banking sector, has lived in Andorra for fifteen years. He studied economics in London, began his career in investment banking, and later worked in hedge funds, always with a focus on risk management.
Two weeks ago, he participated in a conference in Davos, where he shared his reflections on “deglobalisation”, a key issue in today’s global economy and international banking.
Why is digitalisation so relevant at this particular moment?
Because we are no longer talking about gradual improvements, but a complete overhaul of the system: how value moves, how assets are stored, how data is processed, and how trust is established. When technology evolves rapidly, a country must choose whether to lead, adapt, or simply follow. For Andorra, which can act as a kind of laboratory, this presents a genuine opportunity to get things right – in a thoughtful and balanced way.
How did you start your career in digital transformation in Andorra?
I came to Andorra fifteen years ago to take part in the digital transformation of the banking system, primarily focusing on internal processes. At that time, one of the country’s banks where I worked was implementing a major IT system, and my experience proved very useful. Initially, I came for the project, but I stayed because I liked the country and saw that it was possible to work on initiatives that genuinely impact people’s lives.
About four years ago, with the development of the regulatory framework, I saw a clear opportunity: to build a bridge between the traditional economy and the emerging digital economy. And when I say “bridge,” I don’t mean speculation. I mean real services. This allowed us to support clients from the traditional sector who wanted to enter the digital world with confidence, as well as entrepreneurs from the digital economy who needed banking partners capable of understanding and implementing new business models.
Did you have to convince people to invest in cryptocurrencies?
Not really. In fact, we were surprised to discover that many people already owned digital assets and understood how they worked. What was missing, however, was an atmosphere of trust, well-established processes, risk management, and a clear understanding of the proper steps to take. With the right approach, everyone benefits: customers receive better service, and organisations attract greater activity and new clients.
How do you assess the role of digital assets in today’s financial system?
Their presence is still small compared to traditional markets. But the key point is not their current size, it’s the direction of change. Most assets that today exist in traditional forms – stocks, bonds, funds – will eventually move toward digitalisation. When that happens, transaction speed, costs, settlements, and many of the processes we take for granted will change dramatically.
Why did you decide to leave a bank and start a new independent phase?
The moment came when I felt I needed to grow and pursue something different. I’m grateful for what I’ve achieved, but I wanted to create a space where I could share my experience with other market participants, companies, and institutions, helping them understand changes and make informed decisions.
And when you talk about “changes”, you’re not referring to finance alone, are you?
Exactly. We’re talking about artificial intelligence, robotics, space exploration, regenerative medicine, longevity, and many other frontiers that are rapidly approaching because they are all interconnected. My job is to understand these developments thoroughly and translate them into solutions that are both understandable and useful for clients and organisations, with a pragmatic approach and controlled risk.
You were recently in Davos. What was the atmosphere like in January, and what was the main message of this year’s forum?
Technology and economics are becoming increasingly intertwined, and changes are happening at a rapid pace. The transition to digital sovereignty was a key topic of discussion. In the past, we outsourced our infrastructure and data abroad, but now there’s a strong desire to regain control, ensure sustainability, enhance security, maintain strategic autonomy, and reduce dependence on globalisation.
When you talk about digital sovereignty, what exactly do you mean?
It refers to having key infrastructure and capabilities within the country. This includes data centres, cloud technologies, data management, and the ability to make independent decisions in the area of security. Currently, most of the world’s data is stored in Amazon or Google infrastructures. While this is convenient, it limits real control. If your service is located outside the country, your ability to protect against cyber threats is inherently limited.
Does this mean that cybersecurity is becoming even more important?
Absolutely. If you own the infrastructure, you bear full responsibility for its security. This requires substantial investment and a more effective, proactive approach. Concepts like protection, monitoring, and intelligence come into play. Companies like Palantir have developed powerful control models. The fundamental idea is that countries – and, at the very least, their ecosystems – will want to develop similar capabilities tailored to their specific structures and needs.
What advantage does Andorra have that allows it to position itself as a laboratory for digital sovereignty and technological innovation?
Thanks to its size and flexibility, Andorra has the potential to become a “laboratory country”, a place where full architectural systems – hardware, software, communications, and governance – can be tested. It can demonstrate how digital sovereignty in data, systems, and cybersecurity can be achieved through an exportable model. If it works here, a similar approach can be replicated in other countries.
Some experts argue that the future of digital payments is inevitably linked to the digital euro. How do you assess this prospect from the point of view of users and regulators?
The discussion is certainly interesting, but to me, the digital euro seems more like a political decision than a truly transformative tool for ordinary citizens. Effective private solutions already exist for most tasks. The real question is what tangible benefits it will bring to everyday life and how issues like control, transparency, and governance will be addressed. If this tool is genuinely needed, it would make sense to begin by applying it to government spending, setting an example of transparency.
Looking to the future, which product do you believe will see the most growth?
I believe that structured digital deposits are the fastest-growing opportunity. This isn’t about speculation or short-term investments, but about creating mechanisms that allow more people to access stable, secure, and transparent savings with reasonable returns, all within a clear regulatory framework.
With the right regulation and communication, such a product not only expands access to financial services at the local level but can also be exported to markets where banking services are limited. It creates a sustainable model that combines technology, trust, and financial education.